Category

Economy

Category

Fusionism, a new book by Stephanie Slade, a Senior Editor at Reason, attempts to make sense of the seemingly incoherent New Right. Although Slade proposes a renewal of fusionism as a remedy to conservatism’s drift and the challenges facing a divided Republic, the book’s greatest strength lies in its analysis of the trends to date. 

The Republican Party, for all its faults, was supposed to understand (instinctively, if not always intellectually) limited government, rule of law, and the basics of economics. From its elected leaders, though, we have gotten tariffs, increased public debt, dodgy respect for habeas corpus in immigration enforcement, and the Saturday Night Live tragicomedy of DOGE (a virtue-signaling, clumsy, and cruel flash in the pan destined to die on the vine when it removed entitlements from the chopping block). The coalition that constitutes the New Right has abandoned conservatism, and instead sells its own form of populist interventionism. 

Slade starts by painting a rather glum sketch of the contemporary scene. Within the convoluted and heterogeneous mess she labels “the Dissident Right,” she identifies three major strains: 

  1. the predominant national conservatives, who are eager to use the coercive power of the modern administrative state to advance (allegedly) conservative causes and push for national primacy;
  2. the theocons, who dream of “immanentizing the eschaton” by creating a state theocracy to impose (their understanding of) a transcendent moral order;
  3. the neoreactionaries, the Pajama-Boy Nitzscheans who have been given legitimacy to spew their blend of vitriol and conspiracy.

The NatCons have turned their back on the basics of markets and skepticism about administrative power (how sad in this 250th anniversary year of The Wealth of Nations!). The theocons would repoliticize salvation after three centuries of religious tolerance within Christendom. And, beneath all that, the country’s baser instincts toward power and suppression are flourishing within the neoreactionary right. On the other side, the interventionist excesses of American socialism, with DEI, cancel culture, and continued growth of the administrative-welfare state, are equally horrifying. To paraphrase Richard Nixon, we are all interventionists now.

The titular Fusionism is shorthand for the collaboration of old-school conservatives and libertarians that held in America from 1945 to 1989, or thereabouts. Members of that alliance disagreed on details, but shared a horror for the rise of collectivism, the welfare-administrative state, and the existential threat of communism. 

Slade’s personal history of the movement is a rich and readable complement to some of the deeper treatments of the ideas (notably George Carey’s magisterial compendium, Freedom and Virtue: The Conservative/Libertarian Debate, and my own work with Nathan Schlueter of Hillsdale College, Selfish Libertarians and Socialist Conservatives? The Foundations of the Libertarian-Conservative Debate). Slade’s arguments are clean and incisive, and the prose is a pleasure to read, even if Slade occasionally indulges in the journalist’s déformation professionnelle of descriptive wordiness.

Slade points to several explanations for the rise of the Dissident Right: the failed gamble of China’s accession to the WTO without subsequent human rights improvements, the post-2007 bank bailouts, the costly debacle of attempted nation-building in Iraq and Afghanistan, immigration, those left behind by globalization, and the authoritarianism of DEI. 

These are all plausible. But I suspect that Slade is a bit too kind: the American administrative-welfare state is the real villain in this story. First, because it caused most of the problems that have energized the Dissident Right (crowding out of civil society, a culture of dependence, and erosion of the family). Second, because income inequality in the US is associated with cronyism replacing genuine economic activity — a problem exacerbated by the gutting of K–12 and college education standards by educrats, along with the rise of regressive regulation, including job licensing. Third, because the Dissident Right doesn’t see the irony: its proposed use of the state is exactly what generated the outcomes it decries.

In just half a century, the US shifted from teaching Latin and calculus in high school to teaching basic English and algebra in college. It took a mere generation for discourse to collapse from Ronald Reagan’s gentlemanly and beautiful oratory to Donald Trump’s boorish grade-school-level word salad. What happened, in discourse and substance, between 1989 and 2016? Slade points to the populist conservative Pat Buchanan, but we could also mention Dick Cheney; the vice president was more refined, but also a lot more effective at pushing the power of the unitary executive and expanding the administrative state. There have always been “proto-Dissident Right” voices in America, Slade argues, but they were once kept in check by a loose coalition of libertarians, decent folk, fusionist conservatives, and the communist threat. The pre-1968 Dixiecrat segregationists, the Evangelical Christian Right under Reagan, Pat Buchanan, Dick Cheney and the more radical neocons under George W. Bush were always there. But there was always accountability, restraint, and public decency. 

President Trump is tapping into real ills and soul sicknesses in American society and the American economy; but he is doing so in an ugly way that appeals to the lowest common denominator. Even FDR, Huey Long, Bill Clinton, George W. Bush, and Barack Obama, for all their interventionist instincts and actions and their loose interpretations of the Constitution, operated under a veneer of respectability, and showed some shame when they got caught with their pants down.

Slade proposes a renaissance of fusionism as an antidote to the Dissident Right, in a bid to save both the Republic and the Spirit of ‘76. She reminds us that political analysis will require new language. In a similar spirit, I have long argued that the left-right taxonomy once made sense — in post-1789 France, where the left represented the Jacobin radicals like Robespierre, the centrists were today’s classical liberals, and the right favored a return of the monarchy. But the Dissident Right is a misnomer. This modern movement Slade names does not align with the American conservative tradition, and is thus not clearly of “the Right.” Even if it seeks nativist or religious or other allegedly conservative goals, it does so by promoting an increasingly intrusive and muscular central government.

How little we have progressed since 1944, when F.A. Hayek dedicated The Road to Serfdom to “the socialists of all parties.” 

Today’s classical liberals are, indeed, alone in a two-front war. The paternalistic Left and the Dissident Right both aggressively push for social and economic control. Liberty, limited government, and free markets have few defenders. Fusionism is an appealing alliance, as Slade proposes it. But who will be the fusionist warriors for individual liberty? Where are the moderates to defend private property? Where have all the pro-business, small-government, free-trade conservatives gone? We can hope that there is a Nockian Remnant out there, biding its time while the dissident storm passes. In the meantime, the libertarian wing of fusionism stands alone, as core agreements have largely been abandoned by those who still call themselves conservatives, but now need hyphenations to distinguish conservatism from their preferred flavor of interventionism.
In the spring of 1933, American farmers pleaded for help from their newly elected president, Franklin Roosevelt. Hog prices were at record lows, and the farmers wanted the government to do something.

Not one to let a crisis go to waste, FDR took action. Agriculture Secretary Henry Wallace was tasked with arranging the slaughter of millions of pigs in an effort to raise hog prices. Farmers who participated in the federal government’s hog program — later dubbed by economists “the porcine slaughter of the innocents” — were compensated. Their animals were turned into “inedible meat and bone meal,” courtesy of US taxpayers, even as hunger in America hit record highs. 

A country destroying its own food during a depression might sound like economic madness, and it is — but we are once again watching governments ramp up policies that pay farmers to destroy food.

It’s no secret that European vineyards have been disappearing for years. The trend is starkest in Pyrénées-Orientales in southern France: that region “lost nearly half its vines” between 2000 and 2020, The Economist recently reported. Limited access to water and rising energy costs played a role. But vineyards have vanished with increasing speed in recent years, thanks to government policies. 

In 2024, the French government revived a familiar tactic: paying farmers to rip out their vines. Under this national program, farmers can receive roughly €4,000 (about $4,600) for every hectare they remove. If lawmakers aimed to see the country produce less wine and hasten the disappearance of vineyards, that’s what they got.

France typically produces well over 40 million hectoliters of wine annually, but in 2025 it produced just 36 million, according to the French Ministry of Agriculture. Meanwhile, growers in the Languedoc-Roussillon region saw a surge in vines removed last year — roughly 15,000 hectares, an area approaching the size of Washington, D.C., according to The Economist.

Many might assume climate concerns drove France’s policy, but the primary reason resembles the catalyst for FDR’s “porcine slaughter of the innocents”: oversupply.

Global trends show fewer people drinking alcohol, especially Gen Z. Wine has taken a particularly hard hit, even in France, where red wine consumption recently reached an all-time low. French lawmakers say their policy is designed to “rescue” the wine industry from what the ministry described as excessive output.

To the average person, paying vineyard owners to destroy their vines likely looks crazy — but in Europe, it’s business as usual.

For years, the European Union has attempted to micromanage wine production through various incentives, including direct payments to farmers to remove vines. A European Parliament report found that the EU’s 2008 wine reform set an aggressive target: removal of 175,000 hectares with commitments to not replant. (Actual removal totaled 160,550 hectares.)

Now it appears Brussels is intent on ramping up its policy. The EU’s most recent Wine Package will, among other measures, make it easier for countries to make direct payments to farmers to destroy their vines.

“…new rules on State aid would allow Member States to use national financing not only for distillation of surplus wine,” the package reads, “but also for green harvesting (the total destruction or removal of grapes while still in their immature stage) and grubbing up (complete elimination of all vine stocks) of vineyards.”

There’s a certain irony in the policy. 

For decades, the EU subsidized wine production, resulting in surplusses critics dubbed “wine lakes.” Now Brussels wants to ratchet up efforts to rip out vines — to curb the very surplus that bureaucrats helped create.

There’s a senselessness to Europe’s approach that matches New Deal efforts to alleviate poverty by destroying millions of pigs. At least some New Dealers eventually learned their interventionist policies were failing.

“We are spending more money than we have ever spent before and it does not work,” United States Secretary of the Treasury Henry Morgenthau Jr. admitted to Congress in 1939. “I want to see this country prosperous. I want to see people get a job, I want to see people get enough to eat. We have never made good on our promises.”

Morgenthau learned the hard way that trying to engineer a market economy from Washington — through spending, controls, and heavy-handed intervention — produced results far different from those promised. 

We can only hope lawmakers in Europe eventually learn the same lesson. 

Markets aren’t perfect, but they aggregate information from millions of buyers and sellers far better than bureaucrats, who can’t seem to decide whether to subsidize vineyards to boost production or destroy them to raise prices.

These contradictions will do long-term harm to vineyards. That’s a shame. A world with less wine is a less happy world.

Automakers from Germany to Detroit are at a crossroads. Do they produce cars for consumers or for political points? Ford and Volkswagen are finding out what happens when they opt to please the latter at the expense of the former.

In its most recent earnings report, Ford registered a hefty $1.33 billion quarterly loss for Q2 of 2026 that was punctuated by a 10 percent decline in year-over-year sales for Q1 and Q2, along with a 4 percent fall in revenue in Q1. These lackluster results are partly the result of a failed electric vehicle battery venture along with the cancellation of EV programs that received an underwhelming consumer response. Surprisingly, Wall Street’s response was quite different. 

Ford’s shares surged by seven percent despite the quarter’s losses. They rebounded in part due to Dearborn’s optimistic estimates for the rest of the fiscal year. Why the optimism? That rosy picture comes from the automaker’s realization that the road to profit is paved by the wishes of consumers, not politicians. The report acknowledged that consumers want big pickups and SUVs and haven’t been won over by Ford’s EV offerings. 

Ford’s willingness to cut its losses stands in sharp relief against the decisions being made by Wolfsburg, Germany’s Volkswagen (VW). There, Europe’s largest automaker is discovering that the price for ignoring consumers in favor of Brussels’ mandates is lost market share, reduced productivity, and large-scale layoffs. 

In late 2025, EU leadership announced sweeping directives for reaching all-time emissions lows. One of those requirements in the passenger vehicle market requires EU-based automakers “to comply with a 90 percent tailpipe emissions reduction target, while the remaining 10 percent emissions will need to be compensated through the use of low-carbon steel Made in the Union, or from e-fuels and biofuels.” 

Compliance isn’t cheap. After the mandates were approved, VW CEO Oliver Blume announced: “Over the next five years, the Volkswagen Group intends to invest €160 billion. The focus is on Germany and Europe, in products, technologies, production facilities, and infrastructure.” Further, “ we are financing developments in future-oriented fields such as battery cells, software, and autonomous driving.” While not all of these new expenditures are purely driven by compliance costs, these regulations certainly steer capital toward politically favored investments instead of toward consumers’ desires.

This is a classic case of government-induced malinvestment into certain lines of production. Based on the EU regulators’ decrees for a 2035 ban on the manufacturing and sale of internal combustion engines, VW was forced to make politically generated malinvestments. The question to be raised is a simple one: Were these management decisions driven by market signals provided by consumers? The answer has been a resounding ‘no.’ 

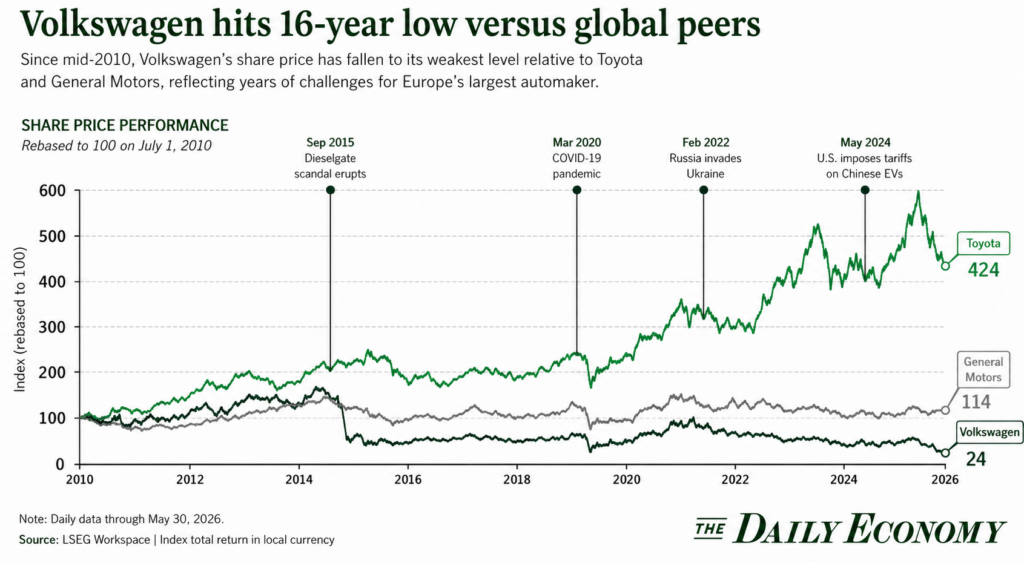
Caught between genuine market signals and mandates from the EU, VW leadership chose to please regulators over customers. Unable to both comply with EU mandates and fend off further market share losses, the Wolfsburg-based manufacturer reversed course on the promise of new investments in July of 2026. They instead announced a 15 percent reduction in the original investment plan to about $148 billion. That’s not all that will be cut. In a recent internal memo, Blume warned that four plants and up to 50,000 additional layoffs may be in order on top of the same number of job cuts already agreed to by Porsche and Audi, amounting to a total loss of 100,000 roles. In response to the proposed cuts, labor representatives for VW workers — IG Metall and the works council — vowed to fight the cuts with their full might. Volkswagen’s labor force isn’t the only group feeling the pain, shareholders have seen the stock sink to its lowest level in sixteen years. 

Data from LSEG workplace

Wolfsburg’s decision to lean into costly EU regulations aren’t the only source of strain. Leadership also cited VW’s 20-percent cost disadvantage relative to its rivals, some of whom are newcomers to the European car market. New electric models from Chinese carmaker BYD have significantly lower labor costs. Meanwhile, US import tariffs have also put a dent in VW and Audi sales stateside, taking a 20 percent year over year slide in Q4 of 2025. 

The first lesson to be taken from these outcomes is that it pays to keep consumers in the driver’s seat, rather than regulators, when it comes to management’s decisions on what types of vehicles to produce. The second is that more regulation means not only higher costs, but market confusion. Relieving automakers from such mixed signals is the surest way to speed toward profitability and satisfied customers.

Ford is now in a better position than VW in this respect, as the Trump administration has scaled back the Biden team’s more stringent Corporate Average Fuel Economy (CAFE) requirements. But there’s still plenty to be undone. The current administration’s estimates indicate that there would be $109 billion in savings to American carmakers by loosening emissions rules. Nevertheless, the rules still require that all US-made passenger vehicles make 34.1 mpg by 2031. That’s a significant reduction from the previous administration’s demands for mpg to reach over 50 mpg. Yet, consumers’ tastes for maximizing fuel efficiency have hit a wall.

This should come as a relief to Ford shareholders and workers, as the sales record for EVs in the US has been less than stellar. For every F-150 Lightning trimline sold, by way of example, Ford lost $44,000. In aggregate, that translated into a $19.5 billion loss on the project before the project was canceled in 2026. According to carbuzz.com, that massive write-down consisted of $8.5 billion for canceled EV projects, $6 billion for a dissolved battery venture, and another $5 billion for program-related expenses. Among EV truck competitors, the Tesla Cybertruck sold 7,000 fewer units than the Lightning and the Chevy Silverado EV sold roughly half of Ford’s 27,000 units. 

As US automakers had been geared up to chase more aggressive CAFE standards, but also in anticipation of future, more stringent regulations, the industry as a whole made massive malinvestments in these technologies, which consumers haven’t adopted. As a result, throughout 2025, GM, Ford, and Stellantis slashed more than 20,000 US salaried jobs, or 19 percent of their combined workforces in the past year, leaving the Rust Belt even more oxidized than it was before. 

While stateside job losses aren’t as stark as those at VW, they are nevertheless a warning sign to auto manufacturers of all nationalities. If pleasing regulators is job number one, then consumers, laborers, and shareholders get left in the dust. This stark reality reveals the high cost of intervention-based innovation versus consumer-driven innovation. The former artificially drives up costs with an unknown payoff. The latter still entails risk, but car manufacturers on both sides of the Atlantic have a far better track record of meeting consumer desires in the markets than in meeting those of regulators and bureaucrats, who are guided by the fickle nature of green politics.

Markets almost never function better when participants know less rather than more. Yet that is where the growing campaign against Federal Reserve forward guidance ultimately leads.

Federal Reserve Chairman Kevin Warsh has argued that the Fed should speak less, publish fewer clues about its future intentions, and move away from many of the communication tools developed over the last three decades. As he told the Senate Banking Committee, “Unlike many of my colleagues past and present, I don’t believe in forward guidance. I don’t believe that I should be previewing for you what a future decision will be.”

The argument sounds sensible enough. Central bankers are often wrong. Forecasts are revised. Policymakers become attached to projections that events quickly render obsolete. Markets sometimes spend more time parsing Federal Reserve speeches than studying the economy itself.

Yet this entire line of reasoning overlooks a basic fact: information does not disappear when it is withheld. Warsh is correct that markets can become overly focused on Federal Reserve communications. But reducing official communication does not eliminate that focus. It merely redirects it. Investors who once scrutinized public statements will instead scrutinize private signals, informal conversations, and perceived access to policymakers. The demand for policy information remains unchanged. Only the transparency of its distribution changes.

The debate over Federal Reserve communication is not really about forward guidance. It is about information.

For most of its history, the Federal Reserve operated behind a veil of deliberate ambiguity. Prior to 1994, it did not routinely announce changes in its target interest rate. Most investors and economists were expected to infer policy changes from open-market operations and subtle shifts in Federal Reserve behavior. Entire industries emerged around deciphering these signals.

This was often described as market discipline. In practice, it frequently rewarded access over analysis. The winners were not necessarily those who best understood inflation, employment, productivity, or growth. They were often those who best understood the habits of central bankers, the mechanics of Federal Reserve operations, and the informal channels through which information traveled.

The move toward transparency occurred because policymakers gradually concluded that this was a poor way to run a modern monetary system. The Fed began announcing rate changes directly. It released more information about its reasoning. Minutes became more detailed. Press conferences became routine. Economic projections became public. Research generally found that markets became better at anticipating policy actions as communication improved and policy surprises diminished.

The intellectual foundation for much of this shift was laid by economists such as Marvin Goodfriend and David Dotsey. In a series of influential papers during the 1980s, Goodfriend challenged what he called the Federal Reserve’s “monetary mystique”—the longstanding belief that secrecy enhanced monetary policy. Dotsey likewise examined the economics of secrecy and concluded that while opacity might reduce some short-run market volatility, it also increased uncertainty by making policy harder to anticipate. Together, their work helped shift the debate from whether central banks should communicate to how they should communicate. Their central insight was straightforward: information not disclosed to the public does not disappear. It simply becomes more valuable to those who possess it, creating incentives for investors to seek privileged access rather than rely on superior economic analysis.

I first encountered these ideas as a doctoral student in economics during the stock-market crash of October 1987. The Federal Reserve of that era was hardly known for openness. Yet when markets were spiraling downward, Alan Greenspan did not choose silence. He issued a brief statement affirming that the Federal Reserve stood ready to provide liquidity to support the financial system.

The statement contained no projections and no dot plots. It simply told markets what they needed to know. The Federal Reserve would act if necessary. One of the most successful acts of forward guidance in Federal Reserve history occurred before economists had even given it a name.

Less than a decade later, I found myself advising central banks and monetary authorities in Kosovo, Afghanistan, Iraq, and Jordan. In each case, the consequences of opacity were impossible to miss. When official information was scarce, markets did not become more efficient. They became more political. Economic analysis mattered less. Access mattered more. Businesses devoted less effort to understanding economic conditions and more effort to discovering what government officials were privately thinking. In weak institutional environments, information itself became a form of currency.

The same dynamic applies to monetary policy.

Suppose the Federal Reserve substantially reduces forward guidance. Will investors stop trying to forecast interest rates? Will banks stop hiring economists? Will hedge funds stop searching for clues about future policy? Of course not.

The demand for information about monetary policy will remain exactly where it is today. Only the supply of public information will decline.

The likely result is not a renewed focus on economic fundamentals. It is a return to a world in which access carries a premium. Investors will spend more time interpreting private signals, cultivating relationships, and searching for clues about policymakers’ intentions. The advantage shifts away from those who are best at analyzing economic data and toward those who are best positioned to obtain information that others cannot.

Supporters of a quieter Federal Reserve are correct that not every speech is useful and not every projection deserves publication. Some communication tools may indeed have gone too far. But the solution to excessive communication is better communication, not deliberate opacity.

Markets are remarkably capable of evaluating information. Investors already distinguish between sound analysis and empty rhetoric. Some Federal Reserve speeches move markets because investors regard them as credible. Others are ignored because investors do not. The real question is whether those judgments should be made using public information or private information.

Markets work best when investors compete on analysis rather than access. The real cost of Federal Reserve silence is not uncertainty. It is privilege.